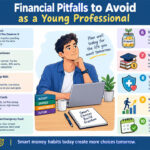
Financial Pitfalls to Avoid as a Young Professional:
Starting your first professional job can feel like a major turning point in life. You finally have a regular paycheck, more independence, and the freedom to make your own financial decisions. At the same time, this new freedom can create financial challenges. It is easy to spend more than you planned, rely too heavily on credit cards, ignore retirement savings, or postpone important financial decisions.
The early years of your career are an important time to develop healthy money habits. Small decisions made today can have a significant effect on your financial situation in the future. You do not need to be wealthy or financially perfect. You simply need to understand where your money is going and make thoughtful choices.
Here are some of the most common financial pitfalls young professionals should avoid.
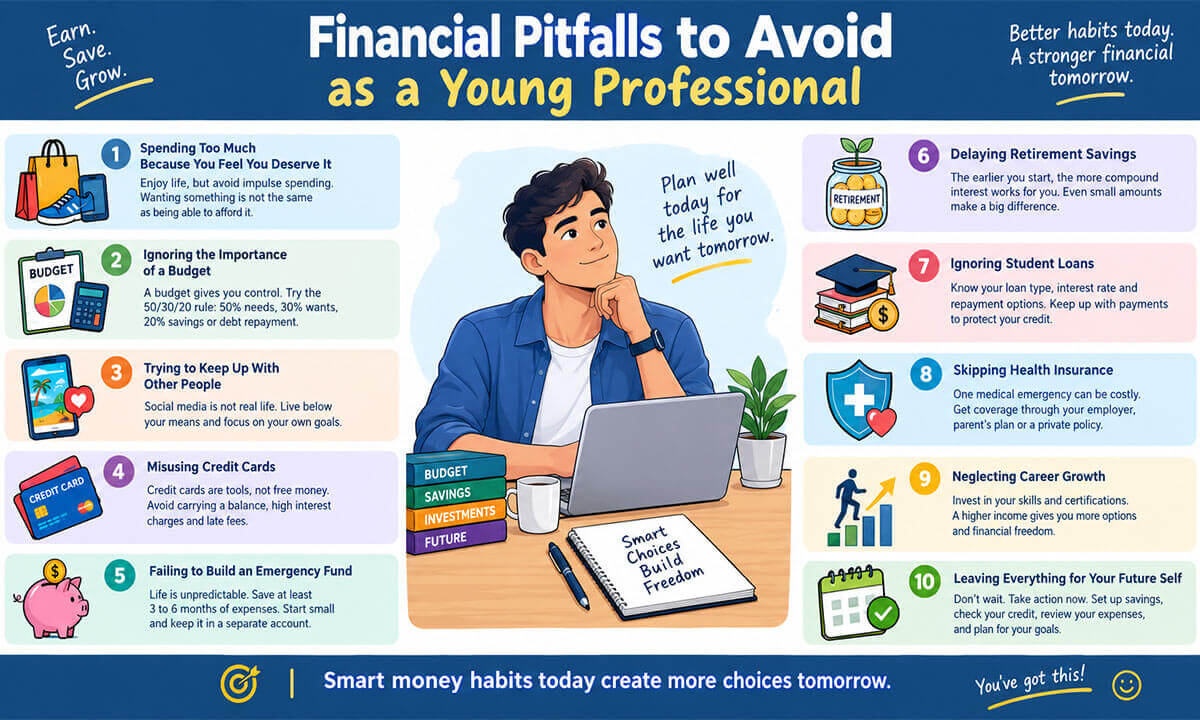
1. Spending Too Much Because You Feel You Deserve It: Getting your first professional paycheck can be exciting. After years of studying or earning limited income, you may finally feel that you can afford the things you have always wanted.
There is nothing wrong with enjoying your money. The problem begins when every paycheck becomes an excuse for unnecessary spending.
You might buy expensive electronics, eat out several times a week, upgrade your phone, take expensive trips, or purchase clothes simply because you can afford them. One purchase may not seem serious, but repeated spending can quickly reduce your savings.
Try to distinguish between wanting something and being able to afford it. Before making a large purchase, ask yourself whether it fits into your financial plan.
Delayed gratification can be a powerful habit. Sometimes waiting a few weeks or months before buying something gives you enough time to decide whether you genuinely need it.
2. Ignoring the Importance of a Budget: Many young professionals avoid budgeting because they think it is restrictive or complicated. In reality, a budget can give you more control over your money.
A budget helps you understand how much you earn, how much you spend, and how much you can save. Without one, it is easy to wonder where your entire paycheck went at the end of the month.
Start by listing your essential expenses such as:
- Housing
- Food
- Transportation
- Utilities
- Insurance
- Loan payments
- Savings
Then identify your discretionary spending, such as entertainment, restaurants, subscriptions, shopping, and travel.
You may also use the 50/30/20 framework as a starting point. It suggests allocating roughly 50 percent of income to needs, 30 percent to wants, and 20 percent to savings or debt repayment. It is not a strict rule. Your actual percentages should reflect your income, location, responsibilities, and financial goals.
3. Trying to Keep Up With Other People: Social media can make comparison particularly difficult. You may see friends buying cars, traveling internationally, moving into expensive apartments, or purchasing the latest technology.
What you see online rarely represents someone’s complete financial situation. A person may have significant savings, family support, debt, or simply be spending more than they can afford.
Trying to maintain a lifestyle because other people appear successful can put unnecessary pressure on your finances.
Instead of asking, “What can I buy to look successful?” ask, “What kind of financial life do I want to build?”
Living within your means may not always look impressive on social media, but it can provide something much more valuable: financial stability.
4. Misusing Credit Cards: Credit cards can be useful financial tools when handled responsibly. They can help establish credit history and may provide certain benefits or rewards.
However, they can also make it easy to spend money you do not actually have.
One of the biggest problems is carrying a balance from month to month. Interest charges can make purchases considerably more expensive than their original price.
Avoid using credit cards for purchases that you cannot reasonably repay. Pay attention to interest rates, fees, payment dates, and other account terms.
If possible, pay the statement balance in full each month. At a minimum, make payments on time so that you do not create unnecessary late fees or credit problems.
The key lesson is simple: a credit limit is not the same thing as available income.
5. Failing to Build an Emergency Fund: Unexpected expenses are part of life. Your car may need repairs. Your computer may stop working. You could lose income or face an unexpected household expense.
Without savings, an emergency can force you to rely on credit cards or loans.
An emergency fund provides a financial cushion for these situations. A common long term target is several months of essential living expenses, although the right amount depends on your circumstances.
Do not worry if you cannot build a large emergency fund immediately. Start with an amount you can manage. Even small, regular contributions can gradually create useful savings.
Keep emergency savings somewhere accessible but separate from your everyday spending account. This reduces the temptation to use it for nonessential purchases.
6. Delaying Retirement Savings: Retirement may seem extremely far away when you are in your twenties. Because of that, many young professionals decide to start saving later.
One of the major advantages young workers have is time. Money invested for retirement can potentially grow over many years through compound growth.
For example, consistently investing a modest amount over several decades can produce a much larger balance than waiting many years and trying to catch up later. Actual investment results will vary, and returns are never guaranteed, but starting early gives your savings more time to grow.
If your employer offers a retirement plan or contribution matching, understand how it works. Consider contributing an amount that fits comfortably within your budget.
You do not have to choose between enjoying your life today and preparing for tomorrow. A balanced approach can allow you to do both.
7. Ignoring Student Loans: Student loans can become a major financial responsibility after graduation. Ignoring them does not make them disappear.
Young professionals should understand exactly what they owe. Review the type of loan, outstanding balance, interest rate, repayment schedule, and available repayment options.
Create a repayment plan that fits your overall financial situation. If you have multiple loans, understand how each one works before considering consolidation or refinancing.
Most importantly, keep track of payment deadlines. Missing payments can lead to additional costs and may affect your credit history depending on the loan and applicable rules.
Financial decisions involving student loans can vary considerably by country and loan program, so make sure you use information that applies to your specific situation.
8. Going Without Appropriate Health Insurance: Being young and healthy does not eliminate the possibility of unexpected medical expenses.
An accident, serious illness, emergency treatment, or hospitalization can create substantial costs. Health insurance can help reduce the financial impact of eligible medical expenses, depending on the policy.
If your employer provides health coverage, learn what it includes and what you are responsible for paying. If you are considering private coverage, compare premiums, deductibles, exclusions, limits, and covered services.
The essential point is to understand your coverage before you need it.
9. Neglecting Career Development: Financial planning is not only about reducing expenses. Increasing your earning potential can also make a significant difference.
Your early career is a good time to develop skills that can improve your future opportunities. Depending on your profession, this might include professional certifications, technical skills, communication skills, management abilities, or additional education.
Do not spend money on courses or qualifications simply because they sound impressive. Focus on learning that has a clear connection to your career goals.
A higher income does not automatically create financial security, but developing valuable skills can give you more opportunities to improve your income over time.
10. Leaving Everything for Your Future Self: One of the easiest financial mistakes is constantly saying, “I will deal with it later.”
You may plan to start saving after your next salary increase. You may intend to check your credit report next month. You may plan to create a budget when you have more time.
The problem is that “later” can easily become years.
Instead, turn financial goals into small actions. Set up an automatic savings transfer. Review your expenses once a month. Check your loan statements. Learn about your workplace benefits. Set a realistic debt repayment target.
You do not have to solve every financial problem at once. Consistent small actions can gradually create better financial habits.
11. Forgetting About Insurance and Financial Protection: Young professionals sometimes focus heavily on savings and forget about financial protection.
Depending on your circumstances, you may need protection such as renters or homeowners insurance, disability coverage, life insurance, or other forms of insurance.
Not everyone needs every type of insurance. The right choices depend on your income, assets, dependents, debts, and responsibilities.
The necessary thing is to understand the risks you face and determine which forms of protection are relevant to your situation.
12. Allowing Lifestyle Inflation to Consume Every Raise: Getting a salary increase is great news. However, immediately increasing your spending every time your income rises can prevent you from making real financial progress.
For example, someone might receive a raise and immediately move into a more expensive apartment, buy a more expensive car, increase restaurant spending, and take more expensive vacations.
As income increases, consider allowing some of the additional money to support savings, investments, debt repayment, and important financial goals.
You can still improve your lifestyle. The goal is to make sure your financial progress improves alongside it.
In conclusion, becoming financially responsible as a young professional does not mean avoiding every enjoyable experience. Money should support your life, not control it.
The most important step is to develop good habits early. Create a realistic budget, control unnecessary spending, use credit carefully, build an emergency fund, understand your loans, protect yourself against major risks, and begin preparing for retirement.
You should also remember that financial progress is not always fast. There may be months when unexpected expenses interfere with your plans. That does not mean you have failed. Review what happened, adjust your plan, and continue.
Your first years of professional life can establish the financial habits that shape the decades ahead. You do not need to have everything figured out today. Start with small, practical decisions and gradually build a financial system that works for your income, responsibilities, and goals.
is an experienced educator and academic currently serving as a Lecturer at Nurul Amin Degree College. With a career dedicated to student development and institutional excellence, he brings a wealth of classroom expertise and pedagogical knowledge to his current role. Before joining the faculty, he served as an Assistant Teacher at Zinzira PM Pilot School and College.